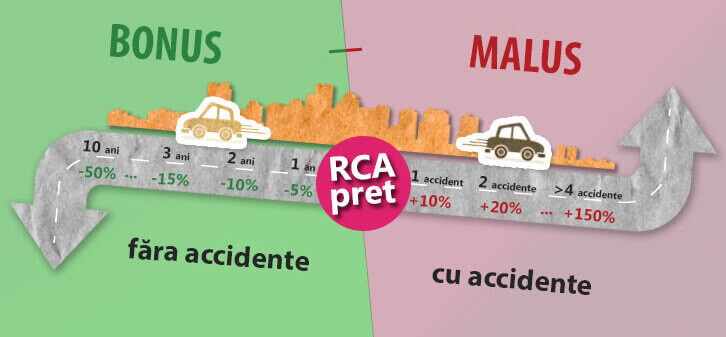
The Bonus-Malus system is a system that establishes a set of discounts and surcharges on the mandatory motor third-party liability insurance premium based on the policyholder's claims history in the previous year, including that of the persons listed in the insurance contract as authorized to drive the vehicle.
Drivers will be penalized when they cause an accident by paying a higher MTPL premium at renewal, while drivers with no incidents will be rewarded with discounts. The maximum penalty leads to doubling the price set in the insurer's rate table, while the maximum discount is 50% of the tariff.
The Bonus-Malus system works as follows: initially, the person (by IDNP) is checked against the contracts database. If, over the last 12 months, the person is found in any insurance contract, whether as the policyholder or listed as an authorized driver, the bonus-malus class assigned to them in that contract is retrieved and considered the starting class. The person is then checked against the claims database. If, over the last 12 months, they are not found to have been involved in any road accidents for which insurance compensation was paid, the person will be assigned the next higher class compared to the starting one, and when calculating the insurance premium they will benefit from a 5% discount, with the discount reaching up to 50% over 10 years if the policyholder has not caused any accident during that entire time.
If an accident occurred during the last insurance contract, the premium increase is applied as follows: for one accident, the premium will increase by 10%, for 2 accidents by 20%, and it may even double if the policyholder caused 4 or more accidents during the previous year.
If, when concluding the insurance contract, several persons are listed as authorized to drive the vehicle covered by the contract, the highest bonus-malus coefficient among those persons' coefficients is applied when calculating the insurance premium.
Individuals and legal entities are also insured according to different criteria. For individuals, the bonus-malus coefficient does not depend on the number of vehicles owned. It is established based on the person's insurance history and is used for all contracts over a 12-month period. For legal entities, the bonus-malus coefficient is assigned per vehicle in relation to the legal entity.